Statistical Arbitrage
We identify pricing differences across digital assets, using systematic signals and balanced long and short positions to pursue relative-value opportunities.
Theo Quant is built by a group of hedge fund managers who don't believe markets can be reliably predicted. We engineer strategies around discipline, not conviction: arbitrage over directional bets.
Since 2022, Theo Quant has evolved from a specialized research group into a firm trading $40M in average daily volume across 19 exchanges, with 40+ counterparties spanning Hong Kong, the Cayman Islands, and the BVI.
We identify pricing differences across digital assets, using systematic signals and balanced long and short positions to pursue relative-value opportunities.
We capture price differences across trading venues through low-latency execution, with exposure limits designed to manage venue and execution risk.
We target pricing and funding-rate differences between traditional equities and their digital perpetual counterparts, using coordinated positions across markets.
The founder series sets out how Theo Quant thinks about risk, backtest rigour, and the execution realities that separate a research result from a deployable strategy.
View all insights
Jackson Wong on risk-neutral quantitative trading and why systematic process supersedes prediction in fast-moving market regimes.
Read full article
An analysis of backtest rigor, execution friction, real-world slippage, and the architecture required to isolate tail risk.
Read full article
On engineering systems designed for multi-decade resilience across changing market structures rather than exploiting transient cycles.
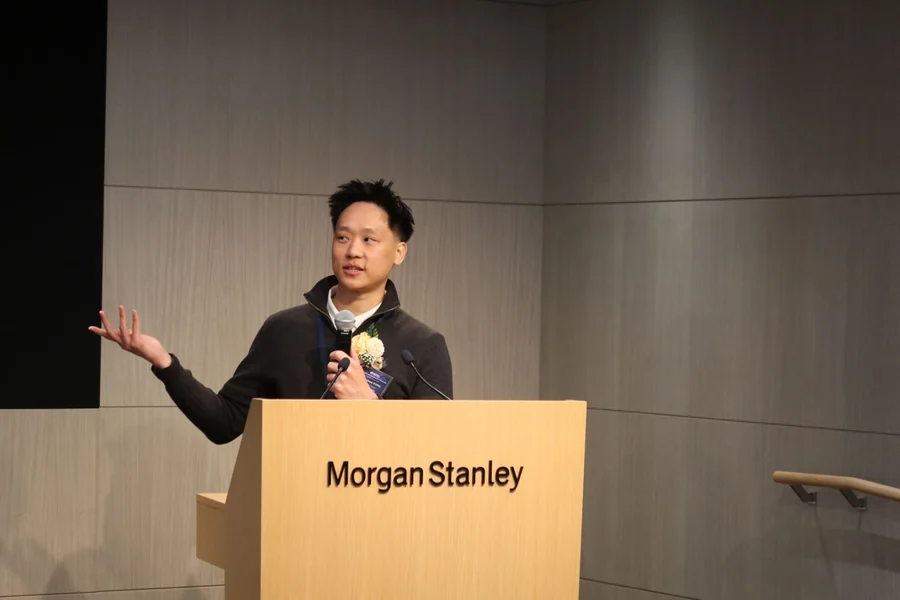
Read full articleJackson Wong served on the Evaluation Committee for the BAPaper2025 Grand Final, a business strategy competition run by the Hong Kong Federation of Business Students for over 40 years. This year's theme: the FinTech revolution for SMEs.
21 November 2025
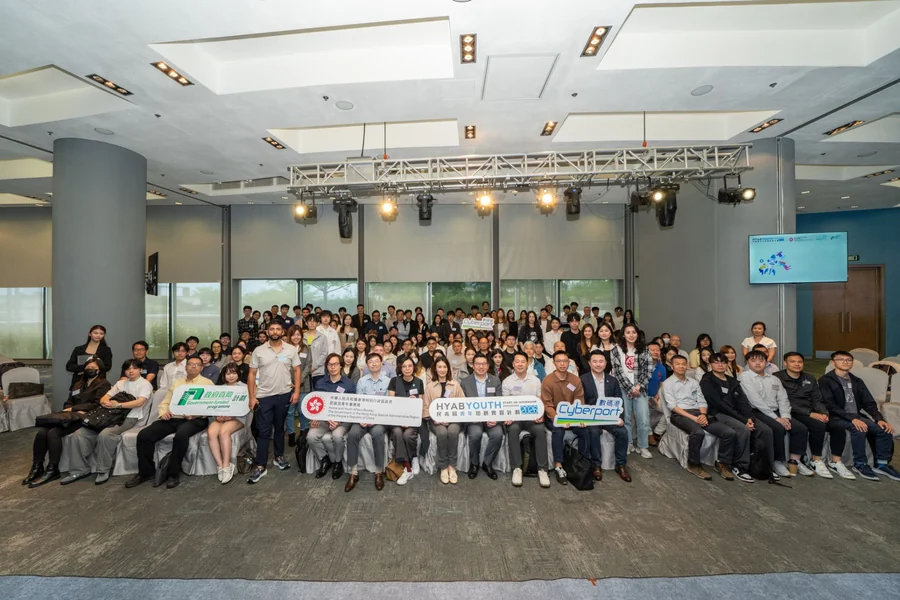
Theo Quant was selected as one of the approved companies under the Home and Youth Affairs Bureau's Youth Start-up Internship Programme 2026, through Cyberport Hong Kong, chosen from over 300 applicants and 4,000 CVs received.
April 2026
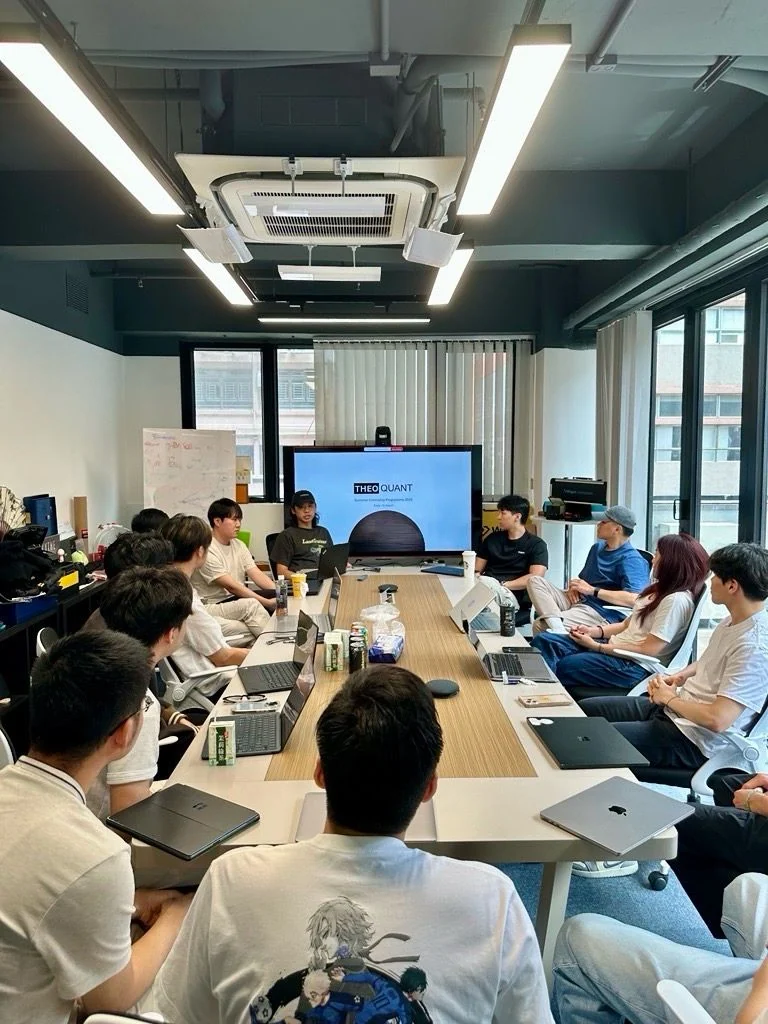
The first cohort of the Theo Quant Summer STEM Internship Program began in 2026. Over seven weeks, interns build their own quant research projects from the ground up, across strategy development, data pipelines, and execution infrastructure.
July 2026
Further materials, including the offering memorandum, are available to qualified investors on request.